-
 by Christian Amegbor
- September 18, 2026
Ghana’s Small Businesses Face a New Tax Era as GRA Expands Modified Taxation Scheme
For many small business owners in Ghana, tax has never been an easy subject.
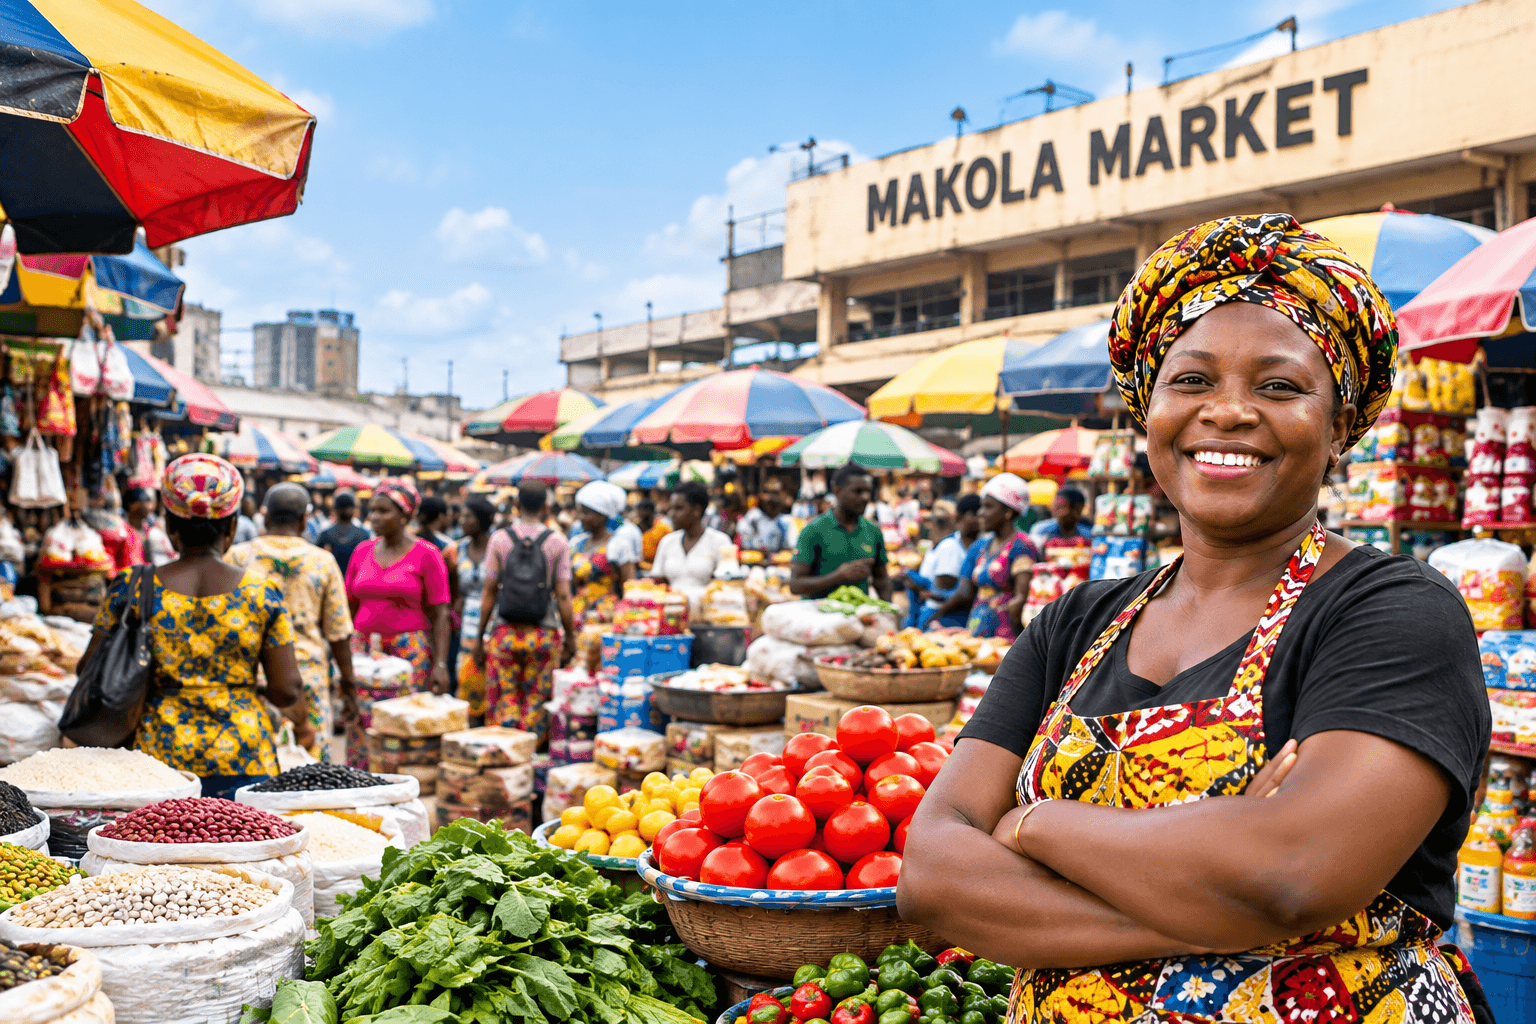
A trader at Makola may know exactly how much she sells in a week but have little time to maintain formal accounting records. A barber may have a busy shop every day but struggle to separate business income from household expenses. A small provision-store owner may be growing steadily without knowing when the business crosses into a different tax obligation.
Ghana’s tax authorities are now trying to make that relationship simpler.
The Ghana Revenue Authority (GRA) has expanded the turnover threshold under its Modified Taxation Scheme, bringing businesses with annual turnover of more than GH¢20,000 and up to GH¢750,000 within the presumptive-tax framework for qualifying individuals.
Under the revised rules, eligible taxpayers in this category are subject to a 3% tax on annual business turnover. The changes took effect on September 1, 2026, following the Income Tax (Amendment) Act, 2026 (Act 1178).
For Ghana’s large informal and small-business economy, the change could have a practical impact.
But understanding what the new threshold actually means is just as important as knowing the figure.
This is not a new tax
One of the easiest ways to misunderstand the reform is to describe the Modified Taxation Scheme as a new tax introduced by the GRA.
It is not.
The GRA describes the Modified Taxation Scheme as a simplified form of Personal Income Tax designed for resident individuals operating in the informal sector. Its purpose is to make tax compliance less complicated while bringing more economic activity into the formal tax system.
The scheme covers people working in areas such as hairdressing, tailoring, mechanics, plumbing, electrical work, food vending and other small businesses.
The latest amendment changes the scale at which the presumptive component applies.
Previously, the GRA's published framework used a lower turnover ceiling. The September 2026 amendment raises the threshold to GH¢750,000 for qualifying individuals under the presumptive arrangement.
That means a business generating GH¢700,000 in annual sales could potentially fall within the framework, provided the owner meets the other requirements.
The 3% figure needs to be understood carefully
The most important detail for business owners is that the 3% is calculated on turnover, not profit.
Turnover is the total sales generated by the business.
Imagine a small trader records GH¢300,000 in sales during a year. At 3%, the presumptive tax calculation would be GH¢9,000.
But that GH¢300,000 is not necessarily what the trader takes home.
The trader may have spent money buying stock, paying rent, transporting goods, paying workers and covering other business expenses.
That is why the distinction between turnover and profit matters.
The Modified Taxation Scheme also has a Modified Cash Basis, under which tax is calculated after allowable business expenses are taken into account. The appropriate category depends on the taxpayer's circumstances.
For small businesses, therefore, the headline figure of “3%” should not be viewed in isolation.
Who can use the scheme?
The Modified Taxation Scheme is aimed primarily at resident individuals whose income comes from their business activities.
The GRA says qualifying taxpayers must be resident in Ghana, earn business income and meet the relevant conditions, including not being registered for VAT for the presumptive categories.
There are also exclusions.
Professionals such as lawyers, accountants and engineers, owners of multiple businesses or outlets, and partners in registered partnerships generally cannot use the presumptive categories and may instead fall under the Modified Cash Basis or the standard tax system.
That distinction is important because the GH¢750,000 threshold does not mean every business with turnover below that amount automatically pays 3%.
The taxpayer's legal structure, business activity and other circumstances still matter.
Why the GRA is pushing the change
The bigger issue behind the reform is Ghana's long-running struggle to bring more economic activity into the formal tax system.
A large number of people earn income through small businesses, trading, services and self-employment. Getting these businesses into a system that is understandable and affordable to comply with has always been a challenge.
If the tax process is too complicated, some businesses may simply avoid registration.
The GRA's argument for modified taxation is that a simpler system can encourage voluntary compliance, broaden the tax base and make it easier for informal-sector operators to meet their obligations.
The latest changes therefore form part of a much wider attempt to reshape the relationship between the tax authority and small businesses.
GRA wants the system to reach small companies too
There is another development worth watching.
The GRA has proposed extending the Modified Taxation Scheme to qualifying small limited-liability companies with annual turnover of up to GH¢750,000.
The proposal was announced during a stakeholder workshop in Accra in September. According to the GRA's policy direction, the change would allow eligible small businesses that operate as limited-liability companies to access a simplified tax regime rather than automatically face compliance requirements designed for larger companies.
This matters because some entrepreneurs formalise their businesses as companies but remain very small in terms of revenue.
A salon, bakery, laundry, carpentry shop or provision store can have a formal corporate structure without having the financial scale of a large company.
The GRA has said its Legal and Policy teams are working with the Ministry of Finance on the legislative changes needed to make the proposed expansion possible.
For now, that extension should be treated as a proposal, not as an existing rule.
Tax compliance is becoming more digital
The reform is also taking place as the GRA increases its use of digital tools.
Under the Modified Taxation Scheme, taxpayers can register through the MTS mobile application, visit a GRA office, receive assistance from a field officer or register through certain trade associations and unions.
The GRA also provides payment options through *880# and its taxpayer mobile application, including mobile-money payments.
For a small entrepreneur who spends most of the day running a business, the ability to register, pay and manage basic tax obligations through a phone could make a significant difference.
But technology alone will not solve the problem.
Business owners still need to understand what they are required to declare, which tax category applies to them and how their turnover is calculated.
What small-business owners should take from the changes
For entrepreneurs, the most important lesson is not simply that the threshold is now GH¢750,000.
It is that the tax system is becoming more structured around the size and nature of a business.
A small trader should know the difference between sales and profit.
A business owner should know whether the business is operating as an individual, sole proprietorship, partnership or company.
And anyone whose business is approaching the VAT threshold should understand that the Modified Taxation Scheme and VAT are separate issues.
The GRA has also raised the VAT registration threshold for businesses dealing in goods to GH¢750,000 under the 2025 VAT reforms. Businesses whose taxable turnover exceeds that threshold are required to register for VAT.
That makes accurate record-keeping increasingly important, even for businesses that consider themselves small.
The real test will be compliance
The success of the reform will ultimately depend on what happens beyond the policy documents.
Can a trader understand the rules without needing an accountant?
Can a small business register without spending days moving between offices?
Can taxpayers trust that the system is predictable?
And can the GRA collect more revenue without making small businesses feel that formalisation is a punishment for trying to grow?
Those questions will matter as much as the GH¢750,000 threshold itself.
Ghana needs a broader tax base, but it also needs businesses to grow.
For many entrepreneurs, the ideal tax system is not one that simply collects more. It is one that gives them a clear set of rules, makes compliance manageable and allows them to understand what they owe as their businesses expand.
The Modified Taxation Scheme is an attempt to move in that direction.
The immediate change is straightforward: qualifying individuals with annual business turnover above GH¢20,000 and up to GH¢750,000 can fall under the 3% presumptive-tax framework from September 2026.
The bigger story, however, is about how Ghana is trying to bring millions of small economic activities into a more organised tax system.
For the country's traders, artisans and small entrepreneurs, the next phase will be about understanding the rules — and making sure that formalisation becomes a pathway to sustainable growth rather than another burden on businesses already operating on tight margins.
Please Login to comment in the post!
you may also like
-
by Christian Amegbor
- September 19, 2026
Government Launches First Phase of Major Toma...
-
by Christian Amegbor
- September 19, 2026
Secured Credit Hits GH¢31.5bn in Q2 2026 as L...
-
by Christian Amegbor
- September 19, 2026
MTN Ghana Steps Up Push to Take Digital Payme...
-
by Christian Amegbor
- September 20, 2026